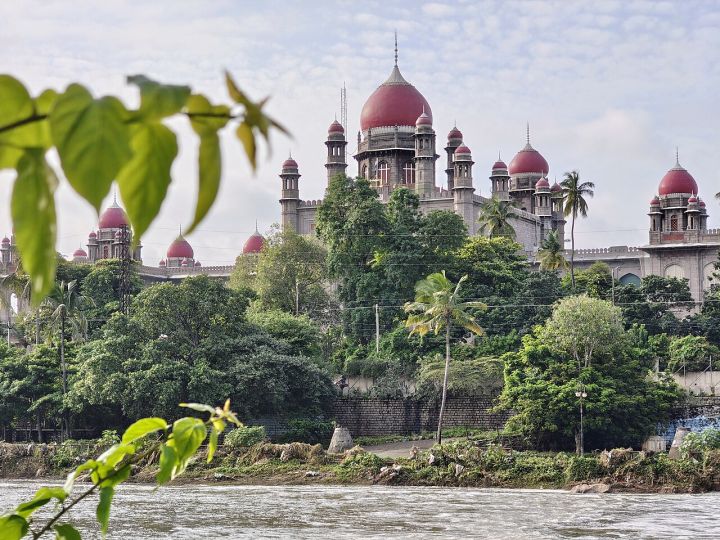
📷 Image: Wikimedia Commons / Kavali Chandrakanth KCK
Business
Telangana HC Permits Eenadu TV Serial Costs as Revenue, Affirms 25% Software Depreciation
✍️ LiveLawBiz
🗓 20 Nov 2026, 04:33 AM
👁 35
The Telangana High Court has ruled that costs incurred by Eenadu TV for its serial productions can be treated as revenue, while also upholding the 25% depreciation rate for software assets.
The Telangana High Court today confirmed that expenses related to the production of television serials by Eenadu TV can be recognized as revenue for accounting purposes. The court also upheld the prevailing 25% depreciation rate for software assets used in the broadcasting process.
This ruling provides clarity for media houses on how to classify and depreciate their production costs, potentially affecting financial statements and tax filings. By treating serial costs as revenue, companies may see a shift in their income statements and asset valuations.
The decision follows a legal challenge filed by Eenadu TV, which sought to align its accounting practices with industry norms. The court’s judgment reiterates existing guidelines on software depreciation, ensuring consistency across the sector.
Industry analysts suggest that the ruling may encourage other broadcasters to reassess their accounting treatments, but the court emphasized that the change applies only to the specific circumstances presented in this case.
This ruling provides clarity for media houses on how to classify and depreciate their production costs, potentially affecting financial statements and tax filings. By treating serial costs as revenue, companies may see a shift in their income statements and asset valuations.
The decision follows a legal challenge filed by Eenadu TV, which sought to align its accounting practices with industry norms. The court’s judgment reiterates existing guidelines on software depreciation, ensuring consistency across the sector.
Industry analysts suggest that the ruling may encourage other broadcasters to reassess their accounting treatments, but the court emphasized that the change applies only to the specific circumstances presented in this case.